Carrara Treatment Wellness & Spa · Malibu
Insurance Coverage for Luxury Rehab at Carrara
A health plan can help with some of the cost of a stay at Carrara, and this is how that works, step by step, from the first call to the authorization.
A health plan can help with some of the cost of a stay at Carrara, and this is how that works, step by step, from the first call to the authorization.
Depending on the plan, insurance can help pay a portion of what treatment at Carrara costs. Which plans contribute, and how much, changes often and is decided by the insurers, not by Carrara.
Luxury rehabs that take insurance can mean several different things by it. Here is what a plan can and can’t do toward a stay at Carrara. A plan weighs the clinical care: medical detox, residential treatment, therapy, psychiatric care. It does not pay for the house on Broad Beach, the chef or the spa, and nobody here will tell you it does. Whatever the plan contributes is applied to your stay. The rest is yours.
The question worth asking anywhere you call is who reads the plan and what they’ll tell you. Here the card goes to our own admissions staff, and the answer comes before any decision.
Six terms come up on every call. Here is what each means for a residential stay.

In-network means a provider has a contract with your plan; out-of-network means it doesn’t. Many PPO plans still pay toward out-of-network care, with a larger share left to you; HMO and EPO plans mostly don’t, except in an emergency. That is how plans work in general, not a statement about Carrara’s status with any plan.
A check, before treatment starts, of what your plan says it will do: whether substance use treatment is a covered benefit, at which level of care, with what deductible and out-of-pocket limit, and whether authorization comes first. Not a promise that the plan will pay.
The plan’s approval of a service before it happens; some insurers call it precertification. Residential and inpatient behavioral health admissions usually need it, and Aetna and Cigna both list them among the services that do.
The plan’s judgment that a level of care is clinically needed, made at admission and reviewed during the stay. A plan can approve residential treatment for a period, then ask for clinical notes before approving more. At Carrara the clinical case for that level of care rests with the medical team. Dr. Craig V. Smith, MD, has board certification in Addiction Medicine and directs that team as Medical Director.
What you pay for covered care each plan year before the plan starts paying. Out-of-network care often has its own, higher deductible.
The most you pay for covered in-network care in a plan year; after that the plan pays covered benefits in full. Premiums, out-of-network care and charges above the allowed amount generally don’t count.
Luxury rehab insurance verification takes one call or one form, and asking commits you to nothing.
Call, or put your plan details into the insurance verification form. The call is confidential, and a spouse or an assistant can make it for you.
Carrara’s admissions team, under Johnna Hose, Director of Admissions, calls the insurer and checks the benefit itself: level of care, deductible, out-of-pocket limit and authorization rules.
What the plan says it will do, what it won’t, and what that leaves to you. If the plan can’t contribute at all, you’re told that too.
If you come, any authorization the plan requires is requested before admission, and Carrara’s utilization review team supplies the notes the insurer asks for during your stay. A denial can be appealed: see how to answer a denied addiction treatment claim.
Each page says how that carrier’s plans tend to work and what Carrara checks. None promises coverage.
Plan types, precertification through Evernorth Behavioral Health, and how a Cigna plan gets checked.
How Aetna plans handle residential treatment, what needs precertification, and what Member Services can tell you.
Independent companies under one name, so the answer depends on your state’s plan and its network rules.
Two people, two plans, two medical-necessity decisions: how coverage works when partners come to treatment together.
These names turn up on insurance cards and in network directories, and people search for them by name. Here is what each one is and how it bears on a stay at Carrara.
MultiPlan, PHCS and Beech Street are PPO networks, not insurance companies. The logo on a card means your health plan rents that network for access to discounted providers; the plan itself decides what it covers and pays the claims. PHCS (Private Healthcare Systems) and Beech Street both belong to MultiPlan, whose parent has been called Claritev since February 2025 and says plainly that it does not offer insurance or administer benefits. So “does MultiPlan cover rehab” has no answer on its own: MultiPlan rehab coverage is whatever the underlying plan provides, and that is what admissions checks.
Beacon Health Options became Carelon Behavioral Health on March 1, 2023. It is Elevance Health’s behavioral health company, and the name change did not alter benefits or phone numbers. Carelon manages mental health and substance use benefits for health plans and employers, so it may be the name that handles authorization even when the medical card says something else. Whether a Carelon-managed plan contributes toward drug rehab at Carrara depends on that plan.
GEHA is a nonprofit association offering Federal Employees Health Benefits plans to federal employees, retirees and their families, and GEHA plans run on UnitedHealthcare networks. What a GEHA plan pays toward drug rehab at Carrara, if anything, follows that plan’s network rules, so the card gets the same check as any other.
The Affordable Care Act doesn’t cover drug rehab by itself. It requires individual and small-group health plans to cover ten categories of essential health benefits, and “mental health and substance use disorder services, including behavioral health treatment” is one of the ten. It also stops a plan turning you down for a condition you already have.
The Mental Health Parity and Addiction Equity Act of 2008 adds that when a plan covers mental health or substance use care, its financial requirements and treatment limits can’t be more restrictive than those on most medical and surgical care. Neither law says what a plan must pay toward a particular program, or what your share will be; that is still the plan. If you believe a denial breaks the parity rule, say so in the appeal.
The cost of residential treatment depends on the level of care, length of stay, and services included in your program. Understanding your options can help you plan with confidence. A good place to begin is how much drug rehab costs.
Understand what goes into the cost of inpatient rehab, from medical supervision and clinical services to accommodations, amenities, and length of stay.
Explore how payment plans for luxury rehab may be structured, what terms to review, and which questions to ask before committing.
Learn about potential financing options for drug and alcohol rehab, including private loans and eligible health savings account funds.
Review Carrara’s available payment methods, including credit cards, wire transfers, and HSA cards, and access the online payment portal.
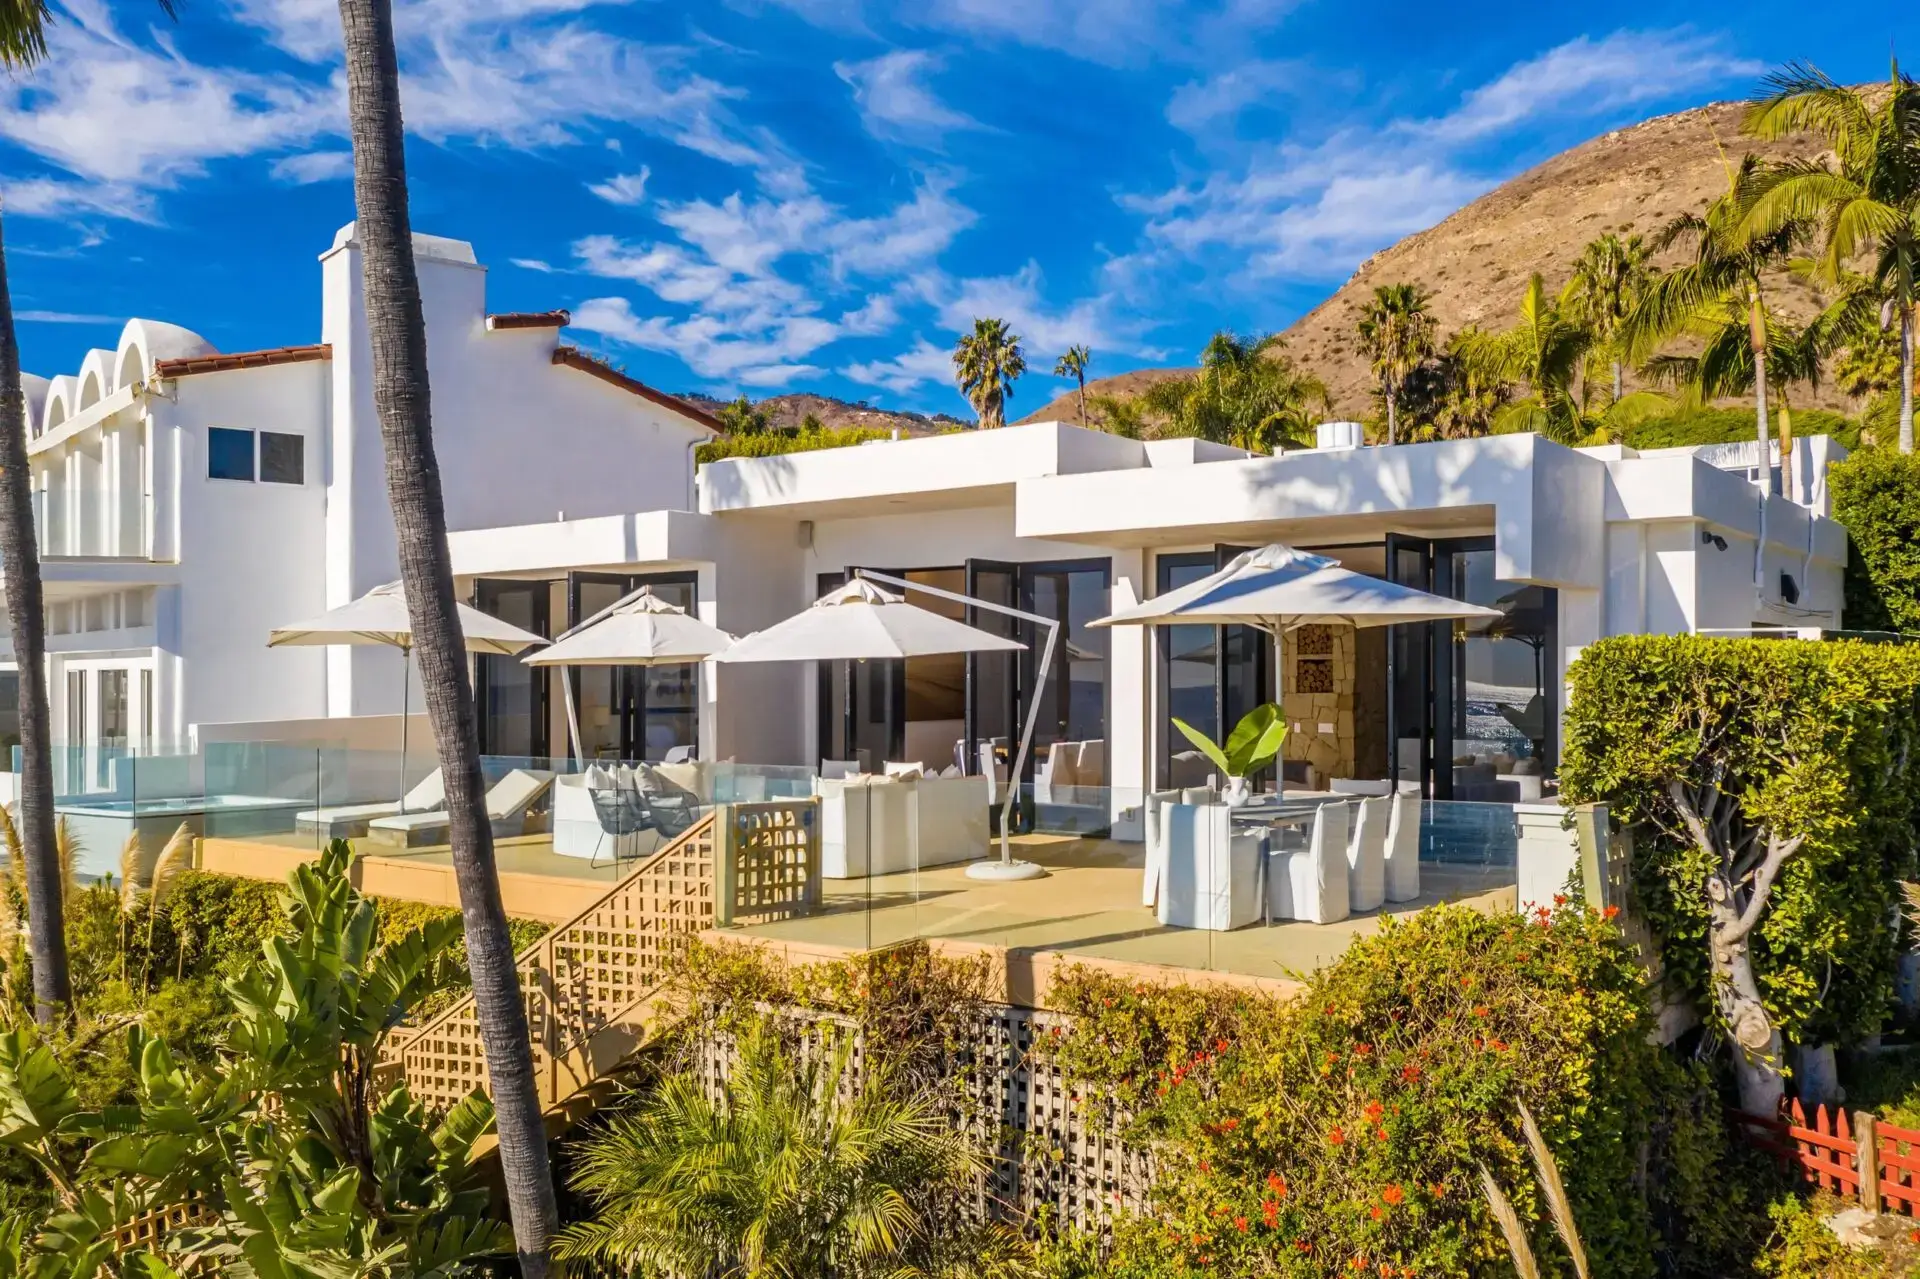
Carrara Treatment is a residential addiction treatment program in Malibu, on Broad Beach, serving Los Angeles and the rest of Southern California. The services are medical detox, residential treatment for drug and alcohol use, dual diagnosis care (depression, anxiety, bipolar disorder or trauma, treated together with the substance use), therapy one-to-one and in groups, psychiatric care, family sessions and aftercare planning. Six clients is the limit, staffed at a 4:1 ratio, with up to 80 one-on-one clinical appointments a month.
PPO plans with out-of-network benefits are the ones most often able to contribute toward a private residential program, because they pay toward providers outside their network. HMO and EPO plans usually pay only in-network, apart from emergencies. That is a pattern, not a promise; the only way to know is to have the specific plan checked.
No. Carrara doesn’t bill Medicaid, Medi-Cal or Medicare, so a stay here can’t be paid through those programs. For what Medicare itself covers at programs that do bill it, see what Medicare pays toward alcohol rehabilitation.
The same check applies. Send the card and admissions reads the plan behind the name: level of care, network rules, deductible and authorization. The name on the card tells you less than the plan does.
Not from Carrara. Nobody here confirms that you’re in treatment without a signed release, beyond the handful of situations the law itself requires, and federal law protects substance use treatment records beyond HIPAA (42 CFR Part 2). Using insurance does create a claims record with your plan, which is one reason some families choose to pay privately; admissions can talk through either route.
Yes, and no. A spouse, parent, assistant or physician can call or send the card, and verification carries no obligation. You can have the answer in hand and decide later.
One call or one form, read by admissions staff who work for Carrara. You’ll know what your plan can do before you commit to anything, and if Carrara turns out not to be the right fit, admissions will tell you.
If this is an emergency, call 911. For free confidential support 24 hours a day, call or text 988.
This page is general information, not medical advice.